I’m not discouraging people from buying RA’s, I’m just saying that they certainly are not the be all and end all of retirement planning. Far from it.
You have certainly pointed out the advantages of an RA. Please balance your argument by pointing out the disadvantages too.
I am certainly not belittling your advice, on the contrary I find your post informative.
I still believe that brokers oversell RA’s, but that’s just my opinion.
I didn’t infer in any way that you are trying to sell the OP and RA.
I just believe that that there are alternatives.
Why not mention them?
I do apologise if my post got your back up, it was certainly not my intention.
Just healthy debate.
There are indeed alternatives but in this instance you have an individual who has made it clear that he does not currently have a pension or provident fund and does not contribute to an RA. It would therefore be in his best interests to have an RA to take advantage of the benefits pointed out by me! If he said he already had a company fund as well as three personal RAs, then great, you'd be perfectly right in questioning why he needs another RA, but this is not the case.
I do not mind healthy debate but when someone seems to have a personal issue with something which they then try and push onto others it becomes less of a debate and more of a personal vendetta of sorts. You claim to be providing balance yet you ask me to point out the negatives. If you are keen to debate why don't you point out the negatives and let's discuss them? Yes, you pay a broker by way of commission but as pointed out I am sure the estate agent who sold you your investment property also got paid for doing their job. It is great to advise someone to do it themselves, and if they had the expertise to do so then so be it (the same applies to the sale of a house too), but the fact that an individual is asking these sorts of questions means they are in need of advice. Should the person that provides this advice not be compensated for it? (Even though here I am providing a lot of it for free

)
I eagerly await the other negatives so we can discuss them.
I have never mentioned market timing.
Your apparently negative reference to an RA as a "fire and forget" investment lead me to draw this conclusion. An RA should be pretty much exactly that. As long as you are invested correctly initially you should not be switching portfolios and trying to time the market.
RA's offer a limited range of rather prudent portfolios as far as i know. And that's how it should be due to their desgin and target market.
.... again I'm not arguing with you.
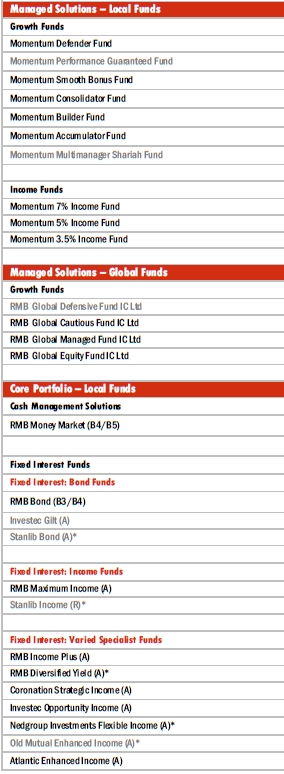
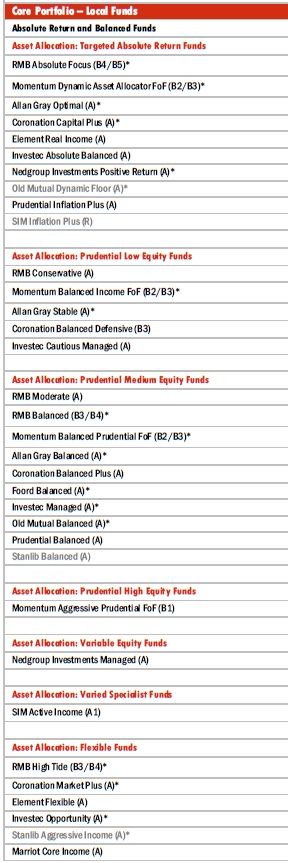
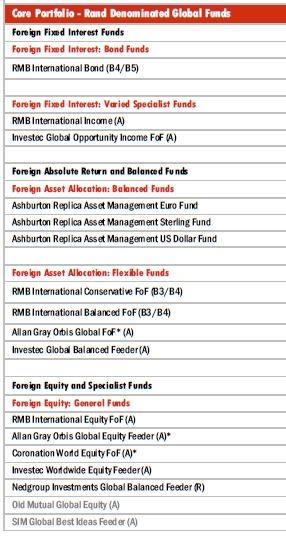
You may not be arguing but you are stating inaccurate information. Perhaps you are muddling your knowledge of pension funds with that of RAs... Let me just use one company as an example, here is a list of the portfolios available on their RA :
Check out
www.equinox.co.za if you want to DIY
Yip, there is also direct investment with Allan Gray if an individual so chooses. You get what you pay for though with direct investment, that is no advise or assistance. Great for someone that knows what they want and what they are doing. The saving is up to three % of each contribution (max allowable commission). If you were to use an adviser, for someone contributing R1000 per month, that is R30 per month or R360 per annum to have someone handle all the paperwork and have someone on call. Forgetting the actual upfront advice aspect, this includes an annual review (or more if you so desire), regular calls to change beneficiaries and the like, the call every year to resend the tax contribution certificate which never arrived in the mail, advice on financial matters totally unrelated to the RA, the call to set your mind at ease about what you have been hearing about markets crashing etc.... Yes, I'm sure you'll argue that this is exaggerating but I can tell you that these things keep me busy most of the time
Bear in mind too that these companies are not doing your investment for free. They still charge management fees, performance fees, annual fees etc. The only thing they don't charge you is an advice fee, because they don't provide advice.
An RA with a life company also has some added perks. They often have things like loyalty/retirement booster (whatever the company refers to it as) bonuses that they pay back to you. If you remain in one company's RA for a period of five years, for instance, you will receive 75% of all qualifying fees paid back to you. So you are getting the advice and you are getting your fees discounted.
Oh, and just to add, I can quite happily provide RAs with the companies mentioned. Obviously I will charge for my advice and time... fair enough I'd say as I do not know many people who work for free.